



Today ... I must speak about long term interest rates and mortgages.
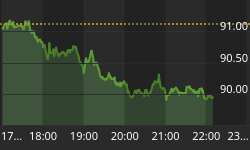
Yesterday, the 30 year yields closed at 44.89. At the end of December, the 30 year yields were only 25.19 ... that was a significant rise (see the chart below). 30 year mortgage rates got down as low as 4.5%, and yesterday they ranged from 5.25% to 5.375%.
When mortgage rates went to 5.25%, there was a 16% drop in mortgage applications. The point is, that the higher mortgage rates rise, the more a recovery in housing is going to be jeopardized.
So, the rise in mortgage rates has been going on for some time and yesterday .... rising mortgage rates finally got the attention of Washington which is now putting pressure on Bernanke to try and keep rates down.
We expect Ben to throw a lot of money at driving rates down in the short term. Longer term, it is a zero sum game for Ben as he has $300 billion left that is earmarked for keeping rates low and the reality is that he probably needs $1 billion to do the job in the next few months.
Why are rates going up? Part of the reason is that there is not enough money for the Government spending levels.
For every dollar being spent in Washington, only 54% is being funded by taxes. That requires the Government to borrow 46 cents for every dollar spent. (Isn't this the formula that got U.S. consumers over leveraged and in trouble in the first place?)
As reluctance to buy bonds and lend to the U.S. Gov. increases, rates have to go higher to compensate for the higher risks.
[To get an approximation of where interest rates should be relative to the TYX 30 year yields:
Take the TYX and divide it by 10 (44.89/10 = 4.489). Then add .761 to .886 to that number. That will give you a range of 5.25% to 5.375% for yesterday's rates. The .761 to .886 are not set in stone ... they represent the current "spread" that banks are marking up long term rates, on mortgages, so they can make a profit. This spread can have a larger change over different time periods reflecting changing market conditions.]